



From self-employed contractors to freelancers, many aspiring homeowners still find themselves locked out by rigid lending criteria designed for a different era of work.
While the UK labour market has seen growth in self-employment and flexible working over the past decade, mortgage lending has lagged behind.
According to the Office for National Statistics, around 4.2 million people in the UK are now self-employed, while many more earn income through a combination of salaried work, freelance contracts, or side businesses.
Despite this shift, high street banks have typically required two to three years of consistent income history, leaving many borrowers unable to meet standard affordability assessments.
However, some regional lenders are beginning to adapt and address the gap.
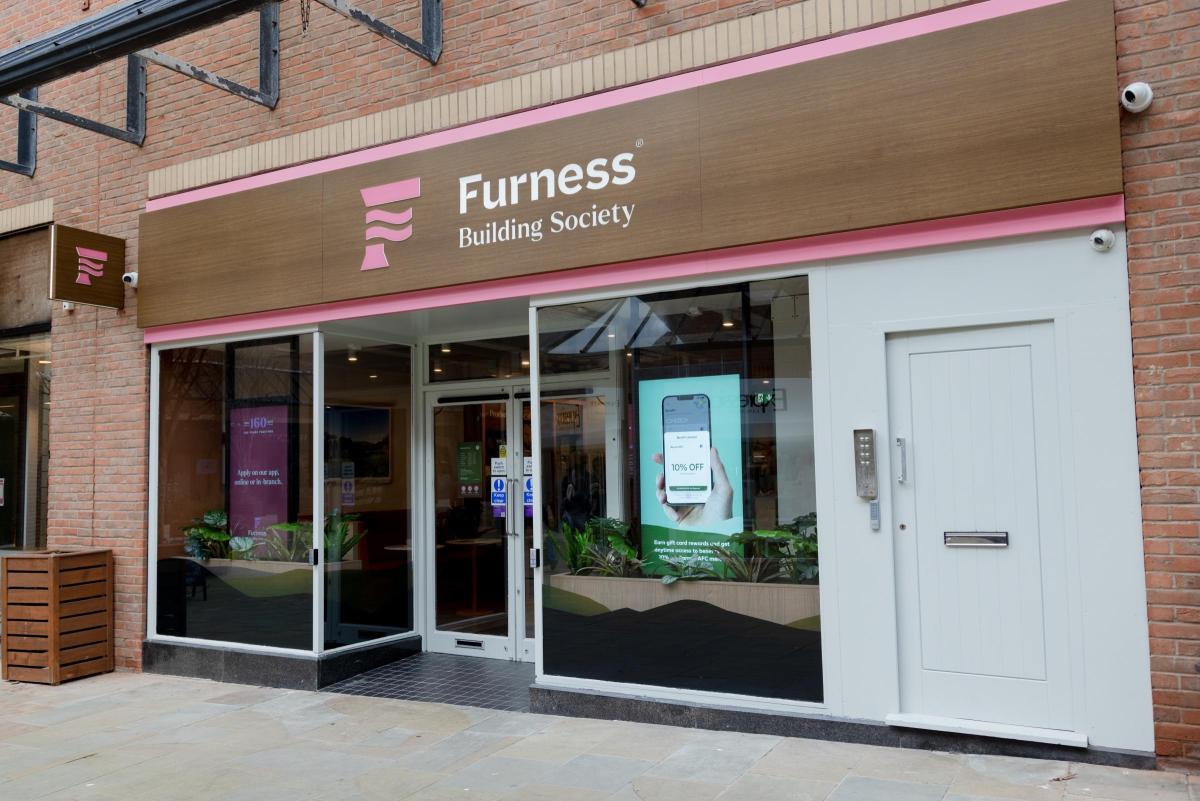
One example in Cumbria is Furness Building Society, which is introducing more flexible lending criteria, including support for applicants with one year of trading history.

The Society also says it is adapting to accommodate a wider range of income types - from contract work, apprenticeships or multiple sources - and offering loans of up to 95% loan-to-value (LTV) for those who qualify.
Average UK house prices are still hovering around £280,000, according to HM Land Registry, so the ability to borrow at higher LTV ratios can make the difference between renting and stepping onto the property ladder. This is especially relevant for younger buyers and those early in their careers, who may have strong earning potential but limited savings.
While automated decision-making has become the norm for many lenders, it can struggle to accommodate borrowers whose financial profiles fall outside standard parameters. Furness says it can assess applications on a case-by-case basis.
Jon Cartlidge, Head of Member and Broker Strategy at Furness Building Society, believes the changes are long overdue: “We know that no two buyers are the same and many people have been unfairly excluded from the market simply because their income or circumstances don’t fit traditional criteria.
“When we look out onto our doorstep, we see local employers who are thriving and we want to do our bit.
“These changes will give more local people a fair chance, whether that’s an apprentice buying their first home, a family wanting to stay in their community or someone who’s been running their business for a year. We’re here to understand real lives and make homeownership possible.
“These changes will give more local people a fair chance, whether that’s an apprentice buying their first home, a family wanting to stay in their community or someone who’s been running their business for a year.”
Also on in-Cumbria:
TALKING POINT: How do you build a longstanding business?
COLUMN: Inheritance tax reform: The business property relief blind spot
How AI is helping UK SMEs recover lost revenue from complex payment systems
Meet the Cumbrian sculptor whose work is displayed across the world
Lidl announces plans to open 50 new UK supermarkets creating 2,000 jobs
The Society also says it is extending support beyond owner-occupiers. For landlords and second-home buyers, increased flexibility includes lending of up to 80% LTV on buy-to-let and holiday-let mortgages - potentially valuable in Cumbria where holiday lets form a key part of the local property landscape.
As the nature of work continues to shift - driven by technology, changing lifestyles and economic pressures - Furness says that lenders who fail to adapt risk excluding an ever-larger segment of the market.
Cases involving self-employed applicants or multiple income streams often require more time and specialist knowledge to place. For regional building societies, there is a potential opportunity to focus on underserved markets and support homebuyers that might otherwise be overlooked.
For borrowers with complex incomes, a mortgage market that better reflects the realities of modern work, and a growing willingness among lenders to look beyond the tick-box approach, could the future of house buying could potentially be more optimistic?

Share